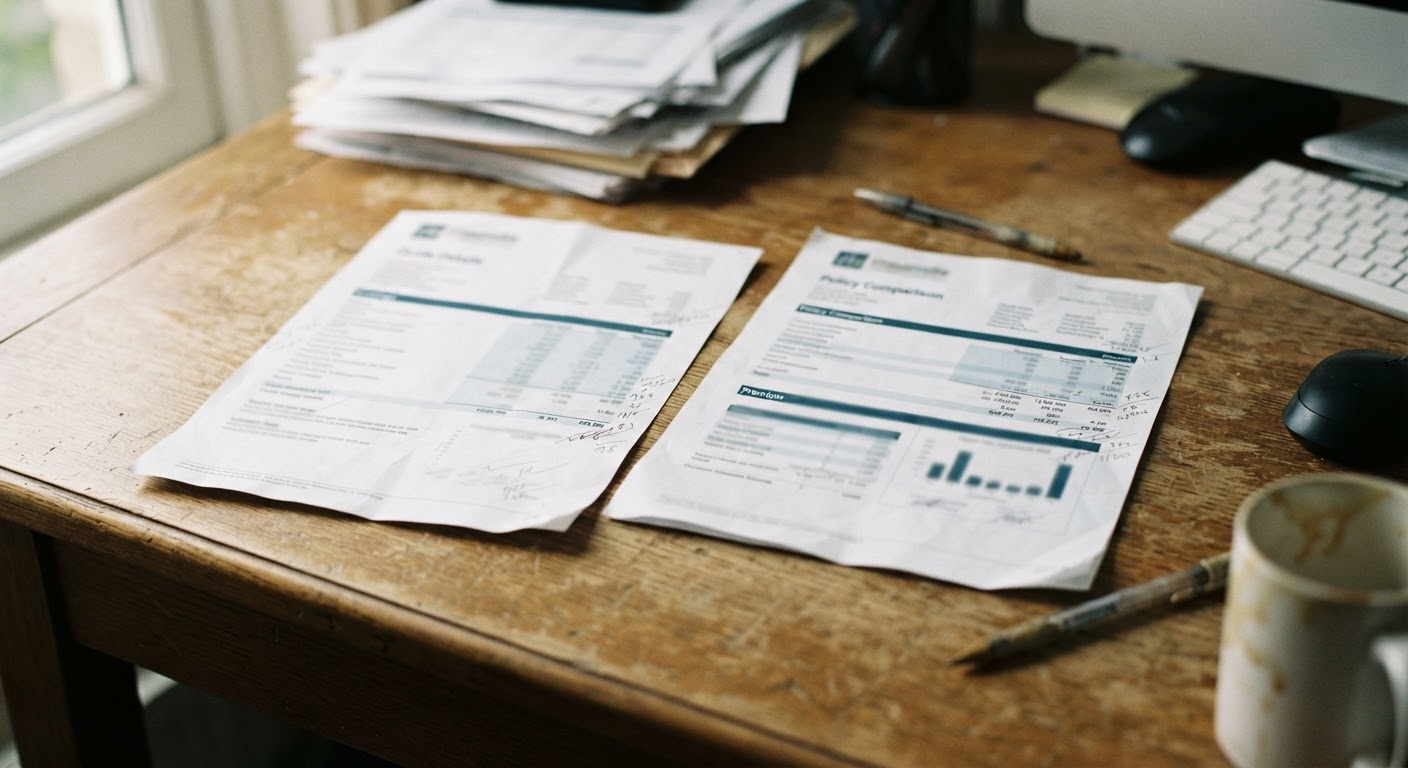
You run the same driver, the same car, and the same coverage choices through two insurers, and the quotes come back hundreds of dollars apart. That gap isn’t a mistake, and it isn’t one company being generous and the other greedy. It’s the predictable result of insurers using different formulas to answer the same question: how likely is this driver to cost us money, and how much?
Understanding why quotes diverge helps you shop smarter. Instead of picking the lowest number and hoping it holds up, you can figure out whether you’re actually comparing two versions of the same coverage or two different products wearing the same label.
Different insurers weigh risk factors differently
Every auto insurer builds its own rating model, and each model is a set of decisions about which factors matter and how much. Two carriers can look at identical applicant data and land on different prices because they’ve made different bets about what predicts future claims.
Some of the variables that commonly show up in rating models include:
- Driving record, including the type and age of violations or accidents
- Credit-based insurance score, where permitted by state regulation
- Age, gender, and marital status
- Where the vehicle is garaged, down to the ZIP code or even the street
- Annual mileage and how the vehicle is used, such as commuting versus occasional use
- Vehicle make, model, model year, and safety or repair-cost data associated with that vehicle
- Prior insurance history, including any lapses in coverage
- Claims history, sometimes pulled across multiple years
The list itself isn’t the interesting part. What matters is the weight each insurer assigns to each factor. One company might treat a single at-fault accident from several years ago as a minor blip. Another might weight recent history much more heavily than older history, so that same accident barely moves the price. A third might rely more on credit-based scoring than either of the others, which means a driver with an excellent record but a thin credit file could see very different numbers depending on which door they walk through.
Insurers also specialize. Some build their books around drivers with long clean histories and price aggressively for that group while charging more for anyone outside it. Others are built to compete for higher-risk drivers and price that segment more competitively, sometimes at the cost of being less sharp on the low-risk end. Neither approach is wrong, but it means your personal profile will simply fit some rating models better than others.
This is also why your quote can change meaningfully if you retest it a year later with no changes to your own history. Insurers periodically update their rating models based on new claims data, adjust how they weight existing factors, or shift their pricing to compete more aggressively in a particular segment. A company that quoted you high last year might be the cheapest option this year, and vice versa, without anything about you changing at all.
Coverage limits that look the same but aren’t
Two quotes can list what appears to be the same set of coverages and still describe very different financial protection. The mismatch usually hides in the details of how limits are structured, not in the headline number.
Liability coverage is the most common place this shows up. Liability limits are typically expressed as a set of numbers representing per-person bodily injury, per-accident bodily injury, and property damage. If you’re comparing quotes, check that all three numbers match across insurers, not just the one that’s printed largest on the summary page. A quote with a higher per-person limit but a lower per-accident limit isn’t strictly better or worse than the reverse — it depends on your situation — but it’s not the same product, and the price difference should be evaluated with that in mind.
Collision and comprehensive coverage add another layer, because the deductible attached to each one changes what you’d actually pay out of pocket if you filed a claim. A quote with a low premium and a high deductible might cost less now but expose you to more cost at the time of a claim. A quote with a higher premium and a low deductible works the other way. Neither is automatically the smarter choice; it depends on how much you could comfortably pay out of pocket on short notice.
Uninsured and underinsured motorist coverage is another area where limits vary independently of the liability limits sitting next to them. Some quotes default this coverage to match your liability limits, others default it lower, and you can typically adjust it either way. If one quote has this coverage set noticeably lower than another, that alone can explain a meaningful chunk of the price gap.
Medical payments coverage or personal injury protection, where applicable, also comes with its own limit, and insurers don’t standardize this the way liability limits are conceptually organized. Look at the dollar limit attached to this coverage on each quote specifically — don’t assume it’s included at a comparable level just because both quotes mention it by name.
The practical habit to build: before you compare two premiums, line up every limit and every deductible on a single sheet, coverage by coverage. If any single line doesn’t match, the quotes aren’t measuring the same thing yet.
Included endorsements that change the comparison
Beyond the core coverages, insurers bundle in a range of endorsements — sometimes automatically, sometimes as optional add-ons you have to select. These extras can make a quote look more expensive when it’s actually including more, or make a quote look cheaper when it’s actually including less.
Common endorsements that show up differently across quotes include:
- Roadside assistance or towing coverage, which some insurers fold into a base policy and others sell separately
- Rental reimbursement, which covers the cost of a rental car while your vehicle is being repaired after a covered claim
- Gap coverage, relevant if you’re financing or leasing and owe more on the vehicle than its current value
- New car replacement or diminishing deductible features, which adjust how a claim is settled on a newer vehicle
- Rideshare or delivery-use endorsements, needed if you use your personal vehicle for platform-based driving work
- Accident forgiveness or similar programs that affect how a future claim influences your renewal price
A quote that appears to be the cheapest option can turn out to be missing several of these, while a slightly higher quote includes them by default. That’s not a flaw in the higher quote — it’s a different bundle. The reverse also happens: a quote can look expensive because it includes an endorsement you don’t need, such as rideshare coverage on a vehicle that never leaves the driveway for work purposes.
Read the declarations page or coverage summary line by line, not just the total. Every insurer is required to list what’s included, but the order, naming, and grouping of these items varies enough that a side-by-side glance can miss something. If a quote includes an endorsement you don’t want, ask whether it can be removed and how much that changes the price — that adjustment alone sometimes closes most of the gap between two quotes.
How to normalize quotes before comparing price
Once you understand that rating models, limits, and endorsements can each vary independently, the fix is straightforward: don’t compare final prices until you’ve made the underlying policies match as closely as possible. Here’s a sequence that works.
- Pull the declarations page or full coverage summary for every quote, not just the price screen. This is where limits and endorsements are actually listed.
- Set every liability limit to the same numbers across all quotes. If one insurer defaulted you to a lower limit, raise it to match the others before you look at price again.
- Match the deductibles on collision and comprehensive. A quote with a $1,000 deductible will look cheaper than one with a $500 deductible on the same car — that’s expected, and it tells you nothing about which insurer prices risk better until the deductibles line up.
- Check uninsured/underinsured motorist limits and medical payments or PIP limits against each other and adjust so they match.
- List every endorsement on each quote and decide, item by item, whether you want it. Add missing ones you want, remove ones you don’t, on every quote equally.
- Re-run the quotes with the normalized selections. Most online quoting tools let you adjust these fields directly and will recalculate the premium in real time.
- Compare the adjusted totals. The gap that remains after this process reflects actual differences in how each insurer rates your risk, which is the comparison you actually want to make.
This process takes longer than glancing at three numbers on a comparison site, but it’s the only way to know whether a cheaper quote is actually cheaper or just thinner. It also puts you in a better position if you decide to negotiate, switch, or adjust your current policy, because you’ll know exactly which levers — limits, deductibles, or endorsements — are moving the price, rather than treating the total as a black box.
Keep in mind that even after normalization, some price difference will remain, and that residual gap is the part driven by each insurer’s own rating model and their appetite for your particular risk profile. That’s normal. The goal of normalizing isn’t to make every quote identical — it’s to make sure the remaining difference is actually about price, not about what you’re buying.